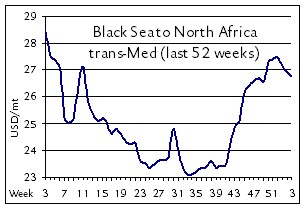
The chartering market is taking a breather. Hopefully it is not the end of the upward rally, although several sources think the market may have peaked. Time will tell. The present indications are certainly down. Kamsarmax owners dropped their rate for a coal cargo from USEC to India by US$ 2.25/mt from US$ 33/mt to secure the cargo. Also from Black Sea charterers were suddenly seeing lower rates than offered and thus reduced their rate by US$ 0.50/mt from US$ 8.40/mt and had no problem to find cover for a cargo to the Continent.
Scrap rates off the Continent have come off by around US$ 2,000 daily for Ultra tonnage for a trip to East Med. Handy rates are still trailing the larger vessels, with 32,000dwt done at US$ 7,750 daily for a trip to West Med. Apparently very pessimistic owners booked a Rouen/Algeria cargo at US$ 14.75/mt for August dates. Grain charterers were rating 36,000dwt at US$ 8,500 daily to cover such similar stem. US$ 8,500 daily was the rate owners of a 32,000dwt were commanding for a trip to West Africa, ending up in South Africa would push the rate up to low US$ 10,000s daily.
For shipbroking insights like this each day, subscribe to the BMTI Daily Report.
 Adriatic Sea market:
 The holidays have continued to linger into 2020 with principals seemingly in no major rush to secure business as long as they can afford to push their requirements down the road. The unexpectedly high momentum that continued into early December and buoyed coaster markets across Europe (from north to south), remains technically in place as far as market fundamentals go, but spot freight trends are looking to move sideways at best into January with charterers expected to start applying more pressure as the month progresses. Owners remain hopeful, however, that adverse weather and their connected delays—as well as the relatively tight tonnage situation of Q4-2019—will keep things moving in their favour for at least another few weeks, but time shall tell if Baltic markets break out of their traditional cycle and do not, in fact, start to slide in January as expected. Northbound freights from the Baltic States to Ireland are fetching decent rates of EUR 30/mt, brokers say, while southbound freights from ARAG (with 5,000mt general cargoes) are securing even better rates of EUR 37-38/mt and higher. There is word, however, that charterers have already secured discounts on those levels for end-month positions.
 [28 NOV 2019] Capital markets have not been overly enthusiastic about shipping in recent years, this past year being no exception, but, according to more than a few finance professionals, this is prime time for a turnaround in fortunes with smart money poised to see solid returns. This is also the opinion of Erik Helberg, CEO of Clarksons Platou Securities, who held a convincing presentation in Hamburg at the 23rd annual