They had a good run, but looking at the declines that have hit the Capesizes at the end of the week, it would seem like classic over-correction being swiftly neutralized following a false dawn of spot market recovery. No route is spared with Pacific round voyages—appropriately, considering their oversized improvements—taking the worst of the decline, losing more than US$ 2,000 to settle in the high teens of US$ 17-18,000. Front haul trips, meanwhile, slip into the mid US$20,000s of about US$ 25,000 daily after fading from the high US$20,000s set at midweek. Voyages have also come under heat as West Aussie rates to China slide to just above US$ 8/mt and Brazil/China voyages fall under US$ 17.5/mt.
If not quite at a boiling point, Panamaxes continue enjoying positive sentiment pushing rates higher yet with TARVs now likely to trade at US$ 14,000 daily (or just below) on early December dates, much improved from the US$ 13,000s of last week and weeks before. Pacific RVs are also holding to just over US$ 9,000 daily on standard 72-76,000 dwt tonnage with a notable upside still very much in place. Front hauls stabilized at around US$ 20,000 daily with slight improvements still more likely than slight discounts. Rumours abound with a market still in flux: period rates, while not taking the market by storm, are still fixed on a regular basis. There is one small Panamaxes (rumoured to be 62,000 dwt) fixed at US$ 19,500 for medium period ex-Veracruz on worldwide redelivery. Nickel ore runs on similar sizes (64-66,000 dwt) from South China have been secured at US$ 8,250 daily via Indonesia and back.
Period chartering seems to be returning to some degree to the Handy bulk sector with US$ 8-9,000 rates being done on Tess 52 tonnage from Southeast Asia on worldwide redel (3-5 months of trading). The big story in the Atlantic remains the USG with US$ 26,000 the newest high water market set for front hauls on Tess 58 ships. In the East, inter-Pacific trips are also fetching middle-high US$ 8,000s with such rates seen on 52-56,000 dwt ships from NoPac booked for trips south to Vietnam or Thailand.
To see more of BMTI’s daily dry bulk analysis, subscribe to the BMTI DAILY REPORT today.
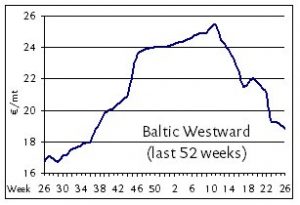 [27 JUNE 2018] With both European holidays and sluggish summer industrial trends setting in, pressure continues to grow on rates in the northern short sea markets even as owners manage to keep discounts limited. Operating costs, as always the basement level for rates to fall, have themselves taken a hit in recent weeks with bunker prices having progressively fallen, giving owners one fewer negotiating tool in keeping rates steady, if not higher. Freights in the high teens of EUR 17-18/mt on the Baltic westward routes from Balticum to ARAG (based on 3,000mt general cargo parcels) have moved slowly but surely into the mid teens of EUR 15-16/mt on the same run, brokers report. ECUK cargoes of 5,000mt are still securing around EUR 10-12/mt, depending on terms, to ARAG. Southbound spot freights remain relatively more attractive as southern European trade regions continue to attract higher activity and firmer rates than their northern counterparts. Agri-prods with stowage of 44-48′ are seen fetching EUR 24-26/mt, traders report, on business from the Upper Baltic to the French Mediterranean, more or less unchanged from rates on the same run since late May. Similar rates are reported as concluded on WCUK/Marmara business. Northbound rates from the Spanish Med to ARAG are fetching high teens of EUR 16-18/mt on mid-size parcels of 5,000mt while the same to the Upper Baltic is getting as high as EUR 22/mt. Upper Baltic to Ireland is still in the lower EUR 20s/mt, we are told, with owners keeping charterers at bay with EUR 21/mt as the lowest offer accepted.
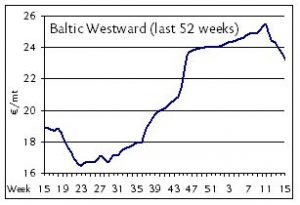 The holiday hangover has lingered over the
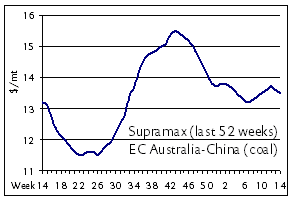 Losses have been rather substantial in the eastern Handy bulk trades in the past week as the monthly switchover and widespread holidays gave charterers all the excuse they needed to get rates reduced toward their preferences. In the event, Supra NoPac rounds lost US$ 500 week-on-week to settle in the lower US$ 11,000s after trading high US$ 11,000s just a week earlier. Indonesia rounds, meanwhile, shed some US$ 300-500 over the week, putting the South China delivery and redelivery round in the high US$ 10,000s of about US$ 10,750 daily on tonnage of 58,000 dwt. Period chartering has been done, though intermittently, with short periods of six months getting US$ 13,000 daily on Handymax tonnage of 54-56,000 dwt from Southeast Asia.